

The International Monetary Fund (IMF) is prioritising revenue mobilisation and financial sector reforms in discussions over a proposed $4.5 billion to $5 billion loan programme for Bangladesh.
The IMF said Bangladesh’s tax-to-GDP ratio had fallen to around 7%, placing it among the lowest in the world. It stressed the need for effective and strategic measures to address existing weaknesses in the financial sector.
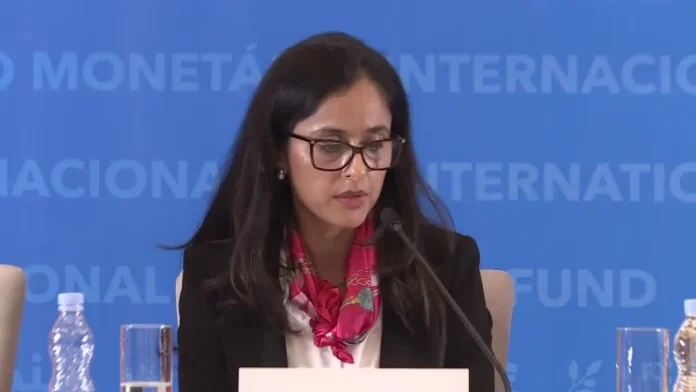
Sonali Jain-Chandra, deputy director of the IMF’s Asia and Pacific Department, made the remarks in response to questions at a press briefing on the Asia-Pacific region on Thursday.
She said Bangladesh needed to increase revenue collection to restore financial sector stability and ensure adequate funding for development activities. She also stressed the need to maintain a contractionary monetary policy until high inflation comes under control and to implement necessary reforms on time.
Jain-Chandra said the IMF was reviewing these issues as part of discussions on a new lending programme for Bangladesh. The organisation is working with the country on revenue mobilisation and financial sector reforms while assessing progress in implementing the measures.
Bangladesh is currently in talks with the IMF to secure a fresh loan of $4.5 billion to $5 billion. The proposed programme may focus on revenue mobilisation, banking sector reforms, exchange rate management and subsidy management.


 is prioritising revenue mobilisation and financial sector reforms in discussions over)